DEBT CONSOLIDATION MORTGAGES IN ABBOTSFORD

If card and loan payments are eating the month, your Abbotsford home equity can replace them with one lower-rate payment. See your number, then talk to us.

When Your Payments Are Running Your Month

None of this is unusual for Abbotsford homeowners who built equity over the last decade. It is a cash-flow problem, not a character one.

A consolidation mortgage swaps several high-interest payments for one, secured by the home you already own. Whether it fits comes down to your equity, your current mortgage and the debts themselves, so we start there.
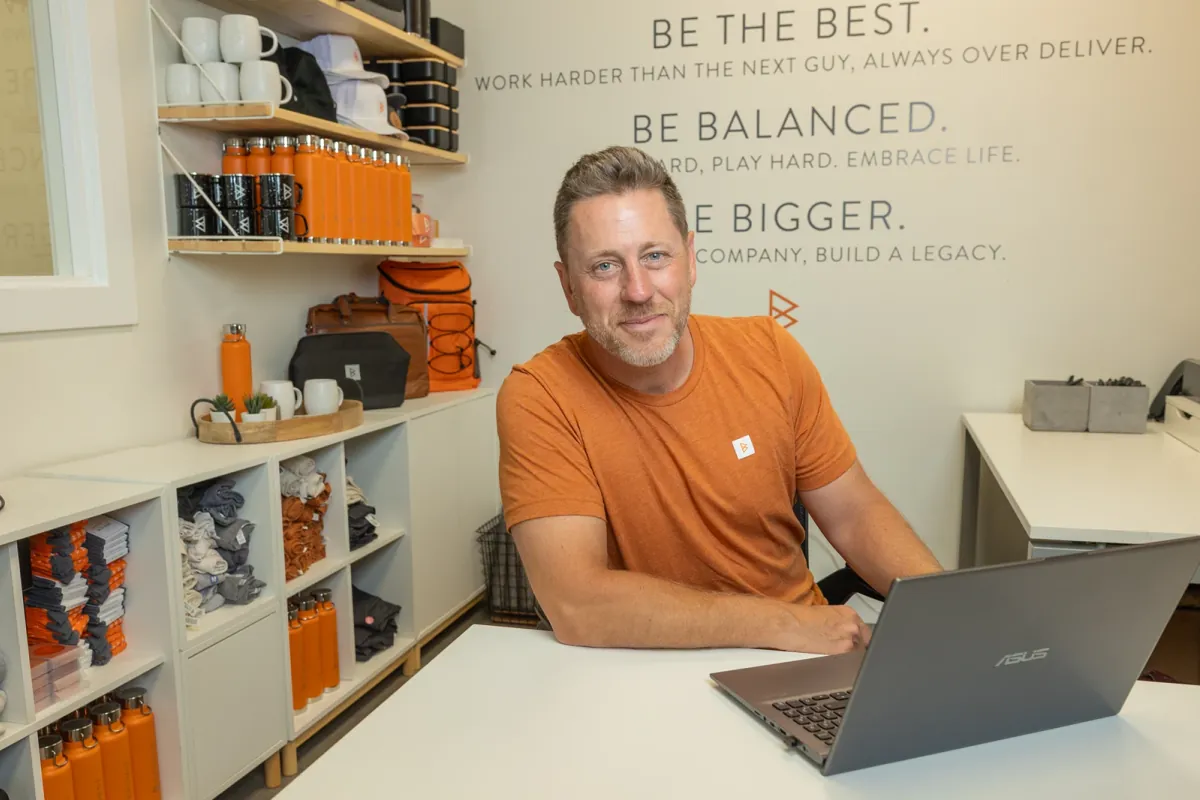
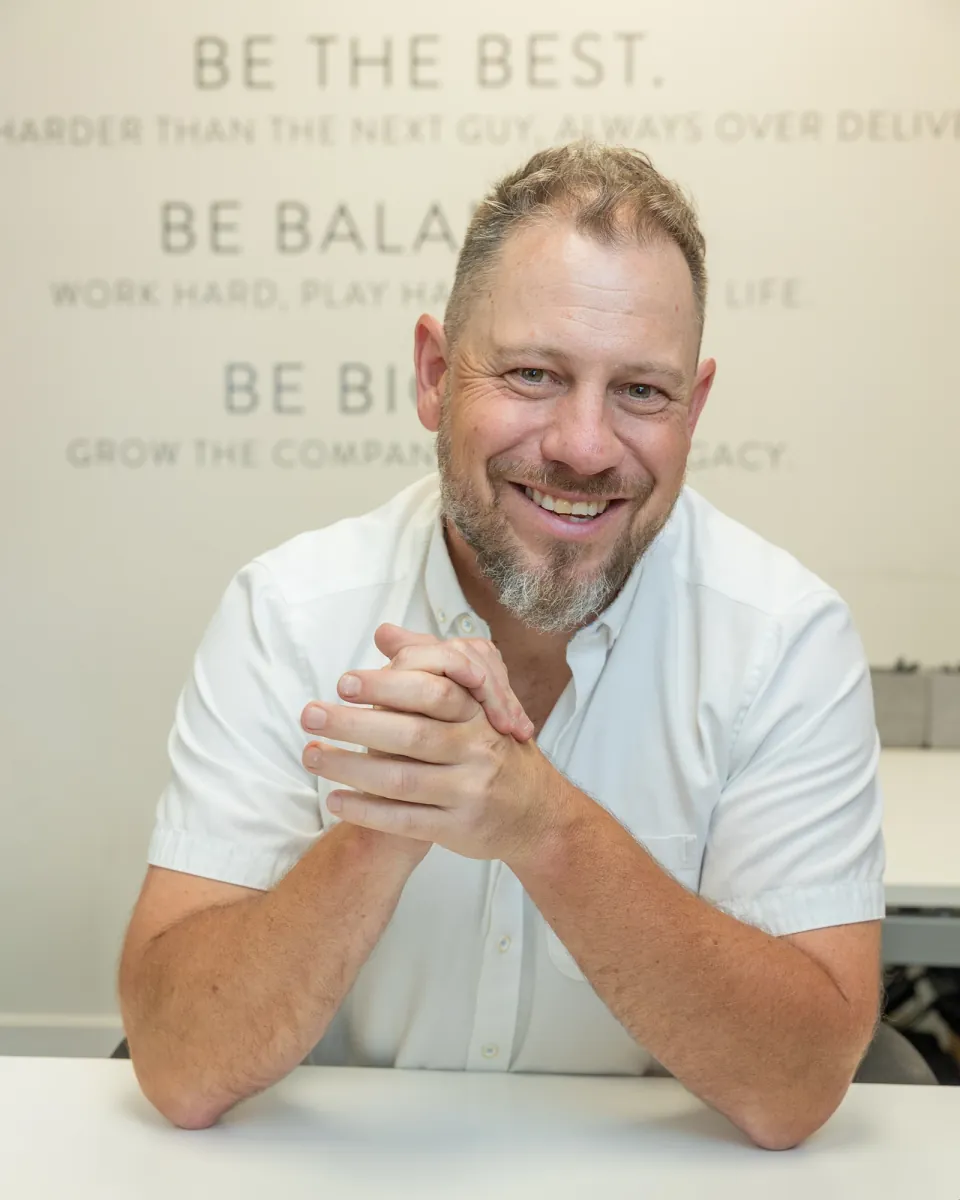
Dave Browne at his desk in the Browne Mortgage office
  • Card balances that keep climbing

    You pay every month and the balance barely moves. Interest takes the payment before it touches much of the principal.

  • Three or four due dates a month

    Cards, a car loan, a line of credit. Each has its own date, its own minimum, and another thing to keep track of.

  • A line of credit that became permanent

    It was meant to be short-term. Years later it is still there, and the interest is just part of the month.

If two of these sound familiar, the next tool is for you.

How Much Equity Can You Use?

This is the first real question. Type your home value, your mortgage, and what you owe. You will see whether a refinance at the 80% cap can cover it. No rate. No payment. No implied approval.

Example numbers. They are labelled so you can tell. Clear them and type yours.

Debts to roll in

Up to five. Add a card, a line of credit, a car loan, or other.

How a Consolidation Mortgage Works

Most of the time this is a refinance. If you want the refinance path in more detail, read our Abbotsford mortgage refinancing page.
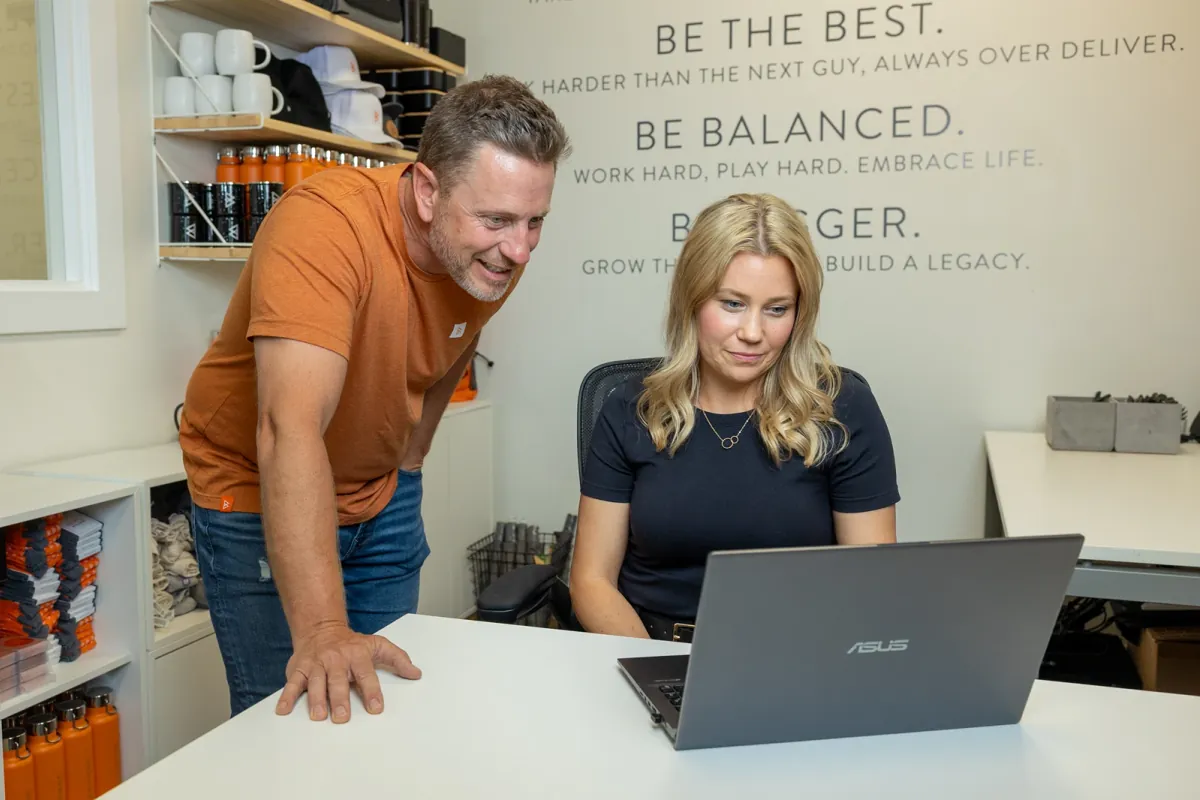
Dave Browne reviewing a mortgage file with a team member in the Abbotsford office
  1. We review your debts and credit

    We look at what you owe and at what rates, then at what a lender will actually see. No judgement. Just the numbers.

  2. We match you with a lender

    We work with 50+ lenders. If an appraisal is needed, that usually happens before anything is final.

  3. The lawyer pays your creditors

    The new mortgage funds usually go to your creditors directly at closing. You typically do not write those cheques yourself.

  4. You have one payment

    Once those balances are paid out, the old due dates stop. You make one mortgage payment.

Refinance, Second Mortgage or HELOC

A refinance to consolidate debt is often the cleanest path. It is not the only one. We will tell you which of these actually fits, not which one is easiest to sell.

Swipe to compare

Refinance

How it works
Replaces your current mortgage with a new one large enough to pay out the debts you are rolling in.
Rate type
Usually the lowest rate of the three, because it sits in first place.
Touches your first mortgage?
Yes. You are breaking or replacing it, which can mean a prepayment penalty.
Best when
You are near renewal, the penalty is small, or the rate drop covers the cost.
Abbotsford refinancing

Second mortgage

How it works
A new loan behind your existing mortgage. The first mortgage stays put.
Rate type
Higher than a refinance, because it is in second place.
Touches your first mortgage?
No. Useful mid-term when breaking the first mortgage would cost too much.
Best when
You need cash now and the penalty on a refinance would eat the savings.
When second mortgages make sense

HELOC

How it works
A revolving line of credit secured against your home. You draw, repay, and draw again.
Rate type
Usually variable. Flexible, which is the point and the risk.
Touches your first mortgage?
Not if it is a standalone line. A blend with your mortgage is a different product.
Best when
You need flexibility and you will not refill the cards. Discipline matters here.
What is a HELOC

What It Costs, and the Limits

The honest version, before anyone asks. No invented prices.

  1. Prepayment penalty

    If you break a fixed-rate mortgage mid-term, the penalty is usually the greater of three months of interest or an interest rate differential. Variable-rate penalties are often simpler. Read our guide to refinancing penalties before you assume it is small.

  2. Legal fees and appraisal

    There are legal fees, and there may be an appraisal. Your Abbotsford broker confirms those costs up front. We will not invent a number here.

  3. The 80% limit, and the stress test

    A refinance can usually go as high as 80% of the home's value. The new mortgage still has to qualify under today's rules, including the stress test. Room on paper is not the same as an approval.

  4. The trade-off

    Spreading short-term debt over a long amortization can lower the payment and raise the total interest. If you go this route, make extra payments when you can so you are not paying card-life debt for 25 years.
Jordi Browne smiling at his desk in the Browne Mortgage office

When Consolidating Is the Wrong Move

We would rather lose the file than put you in a worse spot. These are the cases we say no to, or slow down.

  • If the cards will fill back up

    Rolling the balances in does not change the habit that created them. That is the discipline test. If spending will refill the cards, a larger mortgage makes the problem worse. We wrote this out in using refinancing to consolidate debt.

  • If the penalty costs more than you save

    Breaking a good rate to chase cheaper interest on the cards can be a wash, or a loss. Run the penalty before you run the application.

  • If you could clear it in a year

    A small balance that you can actually pay off does not belong on a 25-year mortgage. Keep the mortgage, keep the plan, skip the refinance.

  • If you are already near 80%

    There may be no refinance room left. A second mortgage or a different product might still be on the table. Stretching past the cap is not.

If any of these is you, we will tell you, and we will talk through what else might work.

Talk to Our Abbotsford Office

Since 2002 we have compared rates from 50+ lenders for Fraser Valley homeowners. The Abbotsford office is the one that takes this file.

3033 Immel St #360, Abbotsford, BC V2S 0E5 Office 604-850-5877
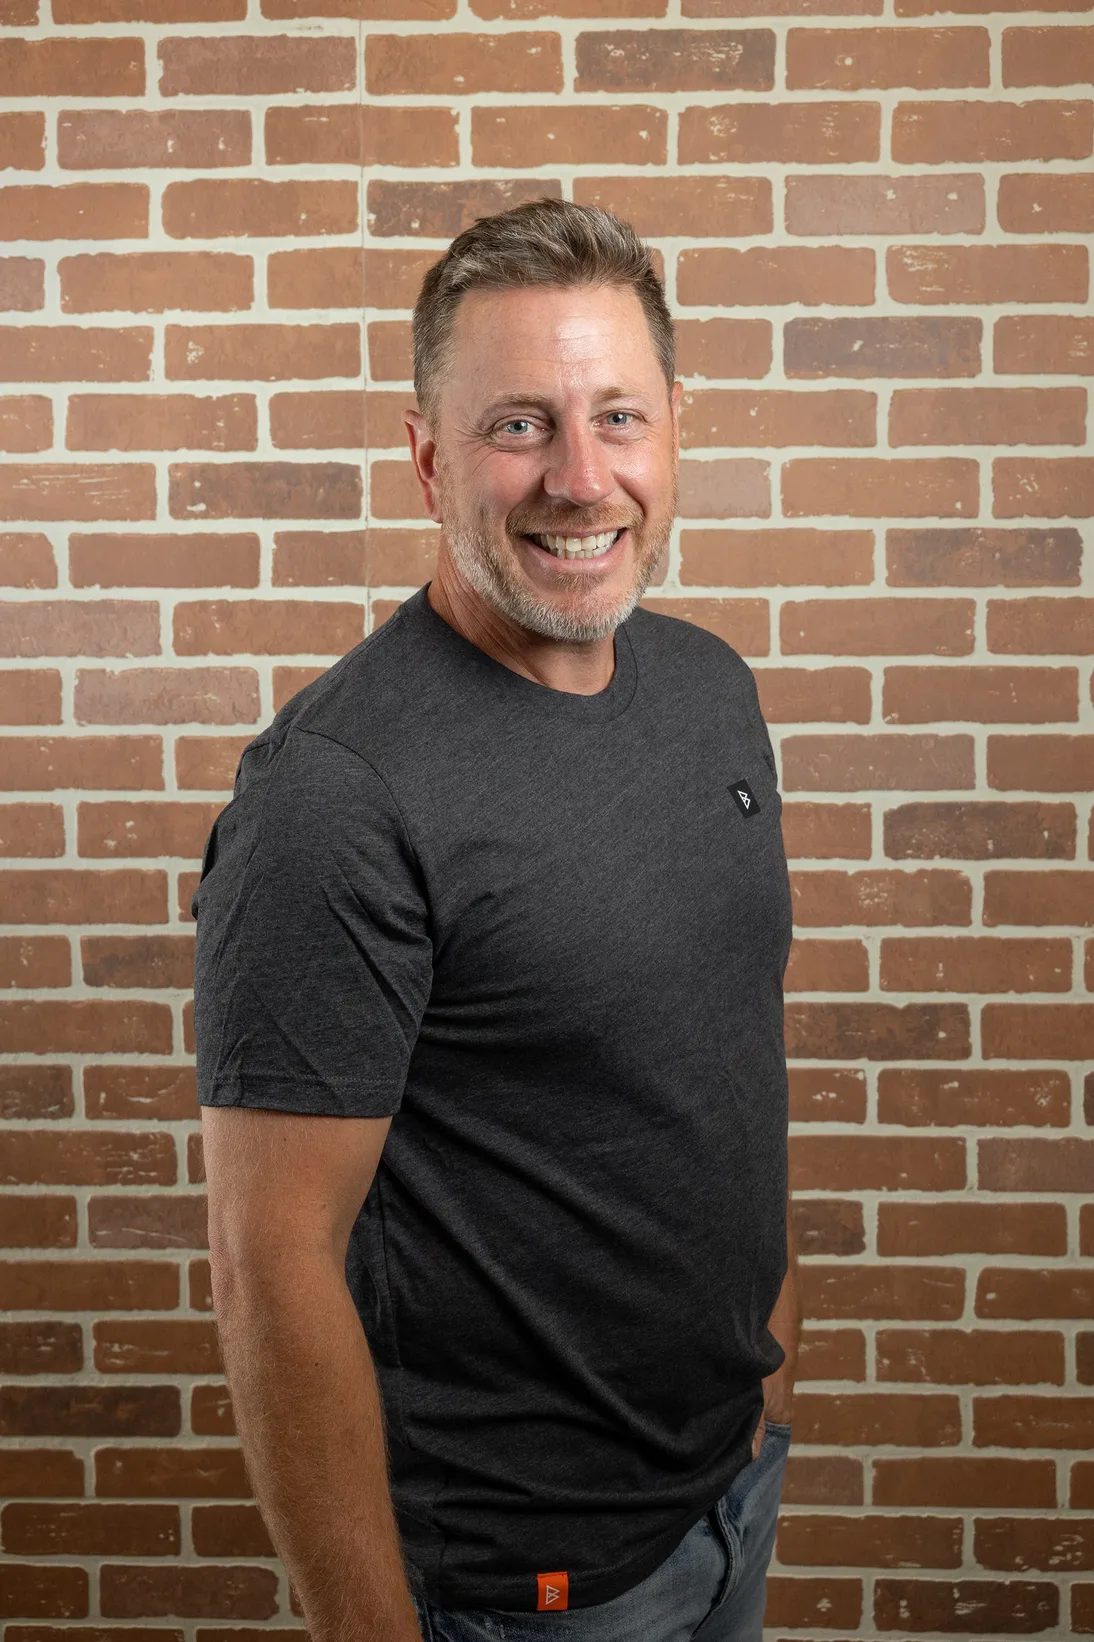
Jordi Browne, founding partner and licensed mortgage broker at Browne Mortgage

Jordi Browne

FOUNDING PARTNER / LICENSED MORTGAGE BROKER

Tel: 1 (604) 615-1312
[email protected]

Dave Browne, founding partner and licensed mortgage broker at Browne Mortgage

Dave Browne

FOUNDING PARTNER / LICENSED MORTGAGE BROKER

Tel: 1 (604) 897-2741
[email protected]

PEOPLE ARE TALKING

Let us help you find a lower rate and get approved

Posted on Google Google
Karlee Kurtz profile picture
Karlee Kurtz
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Dave Saran was incredibly helpful throughout the entire process of purchasing my first home, from always being available when I had questions to getting me the best interest rate! I would recommend Browne Mortgages to anyone! Thanks Dave :)
Posted on Google Google
Cathie Emms profile picture
Cathie Emms
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Dave was a great help, we had lots of questions he was patient and answered them all, it was easy, l would recommend him to anyone that needs a mortgage!
Posted on Google Google
LILY ELLIS profile picture
LILY ELLIS
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Dave and his team were professional, communicative and helped make my remortgaging process as easy and stress-free as it could possibly have been. This is my experience with Browne Mortgage and I wouldn't hesitate to recommend them to anyone.
Posted on Google Google
joseph thorne profile picture
joseph thorne
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
My brother in law recommended Dave Browne to us when we needed to renew our mortgage. It was a great decision. Dave found us the best rate and took care of all the additional details involved. He made the experience easy, pain-free, and stream-lined. We would highly recommend Browne Mortgages.
Posted on Google Google
Rosanne Nielsen profile picture
Rosanne Nielsen
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Dave goes above and beyond and stays with you to the very end and is very encouraging all along the way
Posted on Google Google
Lucas Taylor profile picture
Lucas Taylor
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Really enjoyed working with the Browne group. They kept us informed throughout the entire process and helped us get exactly what we were looking for.
Posted on Google Google
Miranda Green profile picture
Miranda Green
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I had a great experience with Dave! He was very knowledgable and his communication was awesome.
Posted on Google Google
Christina Patan profile picture
Christina Patan
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Dave Saran helped me with acquiring my mortgage. He is professional and had a very strong work ethic. His honesty and motivation we're qualities I admired during this time. I highly recommend any one looking for a mortgage to call him!
Posted on Google Google
Tyler and Sarah Krahn profile picture
Tyler and Sarah Krahn
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Jordi was amazing to work with! We contacted him for a second opinion because it seemed like we’d never be able to afford a home given the information our bank gave us. Jordi gave all the information we needed to confidently pursue a purchase. We found a home we liked and Jordi started working on our financing before we had even left the home. He got us a preferred rate with a lender we were happy with and now 3 weeks later, we’re moved into our new home, and we couldn’t be happier!
Verified by Trustindex
Trustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more

Our Lenders

Every lender has different rules and qualifications that’s why it’s so important to work with one of our brokers so that we can help pair you with the best one to achieve your financing goals.

Debt Consolidation Questions
Sometimes. Prime lenders may say no. B lenders and private lenders are often the path, with a higher rate and more conditions. It is not a yes until a lender underwrites the file.

B lenders and private mortgages

A hard credit check can dip the score for a short time. Paying out cards and loans can help later if those accounts stay closed or at zero. Nobody can promise the score will go up.

Car loans are commonly included. CRA debt depends on the lender and how the debt is structured. Bring the statements. We will tell you what usually qualifies before you apply.

It depends on the appraisal, the lender, and how complete your file is. Some files move in a couple of weeks. Others take longer. We will not quote a number we cannot keep.

Not always. A refinance replaces the first mortgage. A second mortgage or a HELOC can leave the first one in place if the penalty would cost more than you save.

When second mortgages make sense

A refinance can usually go to 80% of the home value, so you typically need enough remaining equity after the current mortgage to cover the debts. If you are already near that cap, the estimator will show it.

See how much equity you can use

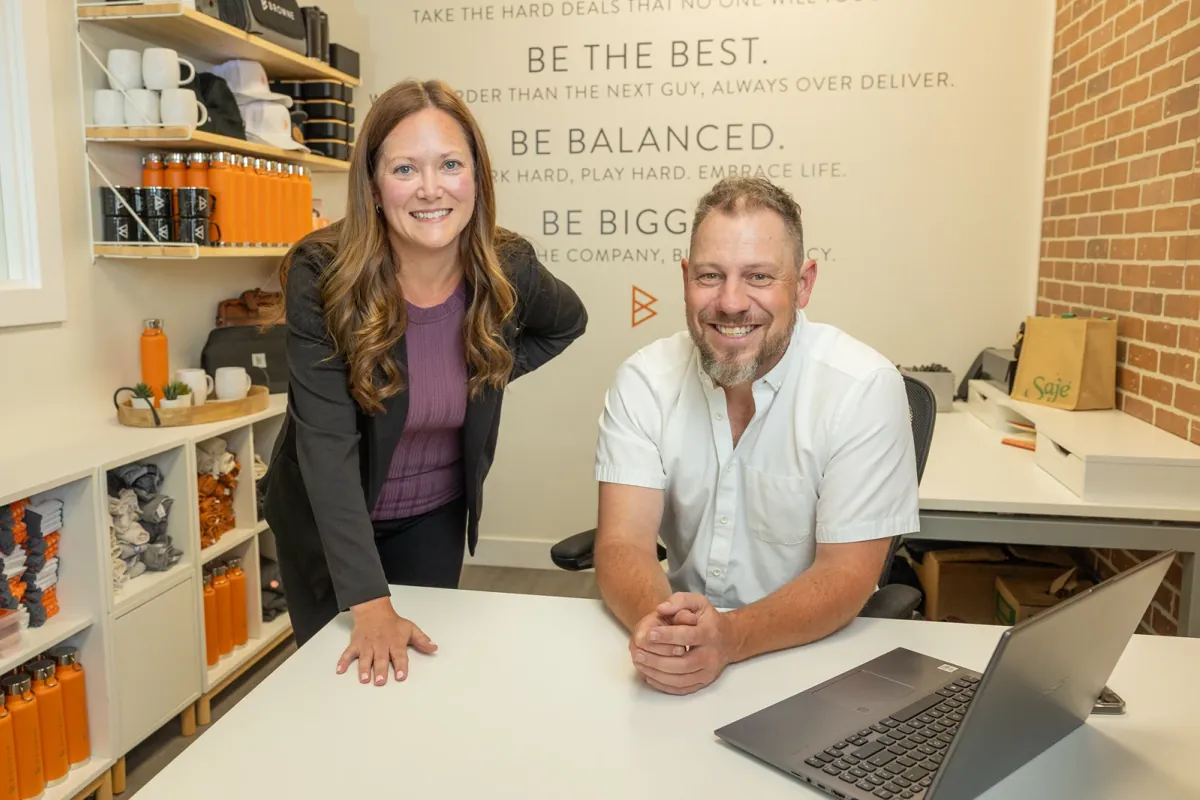
Angela Byrne and Jordi Browne in the Browne Mortgage office

Rather talk it through? Call the Abbotsford office at 604-850-5877.

Start With a Free Debt Review

Send us your details and an Abbotsford broker will look at your debts, your equity and your options. No cost, no obligation.

Ready for the full application? Apply online.