When Income Suddenly Stops Losing your job is stressful under any circumstances, but when you have a mortgage, the pressure multiplies. Your monthly payment does not pause while you search for new employment, and the consequences of missed payments can be severe and long-lasting. The
Investment Property Mortgages Are Different Buying a rental property in the Fraser Valley can be an attractive investment, with steady demand from renters and the potential for long-term appreciation. But financing an investment property is not the same as financing a primary residence. Lenders apply
The Rule That Changes Everything If you have started looking into buying your first home, you have probably encountered the mortgage stress test. It is one of the most significant factors affecting how much you can borrow, and many first-time buyers do not fully understand
A Second Home Is Not an Investment Property Many Fraser Valley residents dream of owning a vacation property in the mountains, at the lake, or on the coast. Financing a second home is different from financing a rental property, and understanding the distinction helps you
The Question That Keeps You Up at Night If you are renting in the Fraser Valley, you have probably had this thought: should I keep renting or should I buy? It is one of the biggest financial decisions you will make, and the answer is
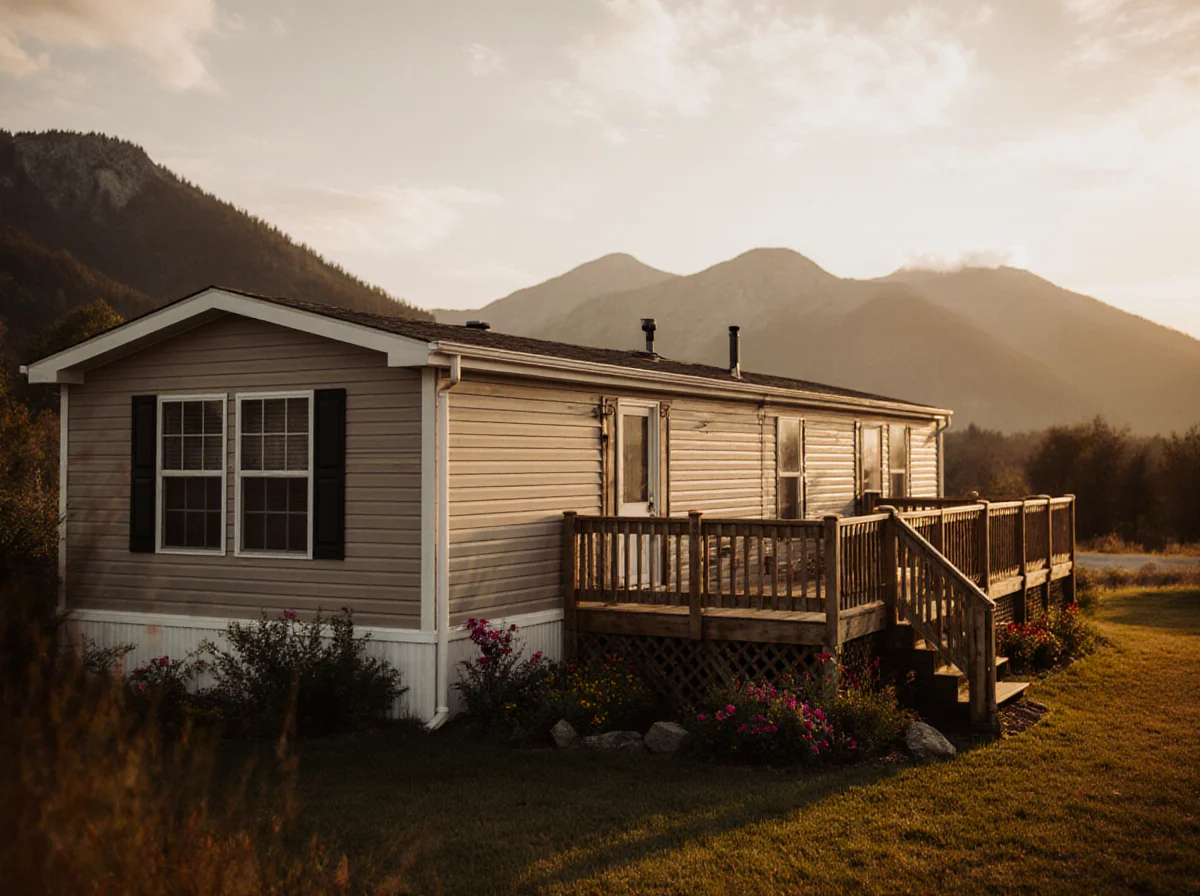
Manufactured Homes Are Not Mobile Homes If you are considering a manufactured home in the Fraser Valley, the first thing to understand is that the terms matter. Mobile homes and manufactured homes are not the same thing when it comes to mortgage financing, and the
It Is Not Just the Down Payment First-time home buyers often focus exclusively on saving for a down payment. It is the biggest number, the hardest to save, and the one that gets all the attention. But buying a home involves many other costs, and
A Strategy Most Homeowners Have Never Heard Of The cascade mortgage strategy is one of those approaches that sounds complicated but is actually simple once you understand the concept. It is a way of structuring your mortgage into multiple segments with different terms, so that
The Down Payment Question Ask anyone about buying their first home and the conversation quickly turns to the down payment. How much do you need? Where does it come from? Can you really buy a home with only 5% down? The answers depend on the
The Debt Consolidation Dilemma If you are carrying high-interest debt, the numbers can be sobering. Credit cards at 20% or more. Personal loans at 10% to 15%. Lines of credit that seemed manageable until they were not. The interest piles up fast, and minimum payments