Mission's combination of lower purchase prices and stable rental demand has caught investors' attention. Properties here cost significantly less than equivalent homes in Maple Ridge or Langley, while rents haven't dropped proportionally. Add consistent tenant demand from commuters, local workers, and students, and the cash
Mission homeowners who've held property through the past decade are sitting on equity they may not have fully considered. Whether you bought a downtown character home years ago or moved into Cedar Valley when the first subdivisions opened, your property value and mortgage balance have
Mission has always attracted people who work for themselves. The district's mix of rural land, small-town character, and proximity to larger markets creates a natural base for trades contractors, home-based businesses, agricultural operators, and remote professionals. If you're self-employed and looking to buy or refinance
The interest rate on your mortgage determines what your home actually costs over time. For a Mission buyer considering a $650,000 purchase, the difference between a 4.5% and a 5.5% rate works out to roughly $320 more per month, or over $19,000 across a five-year
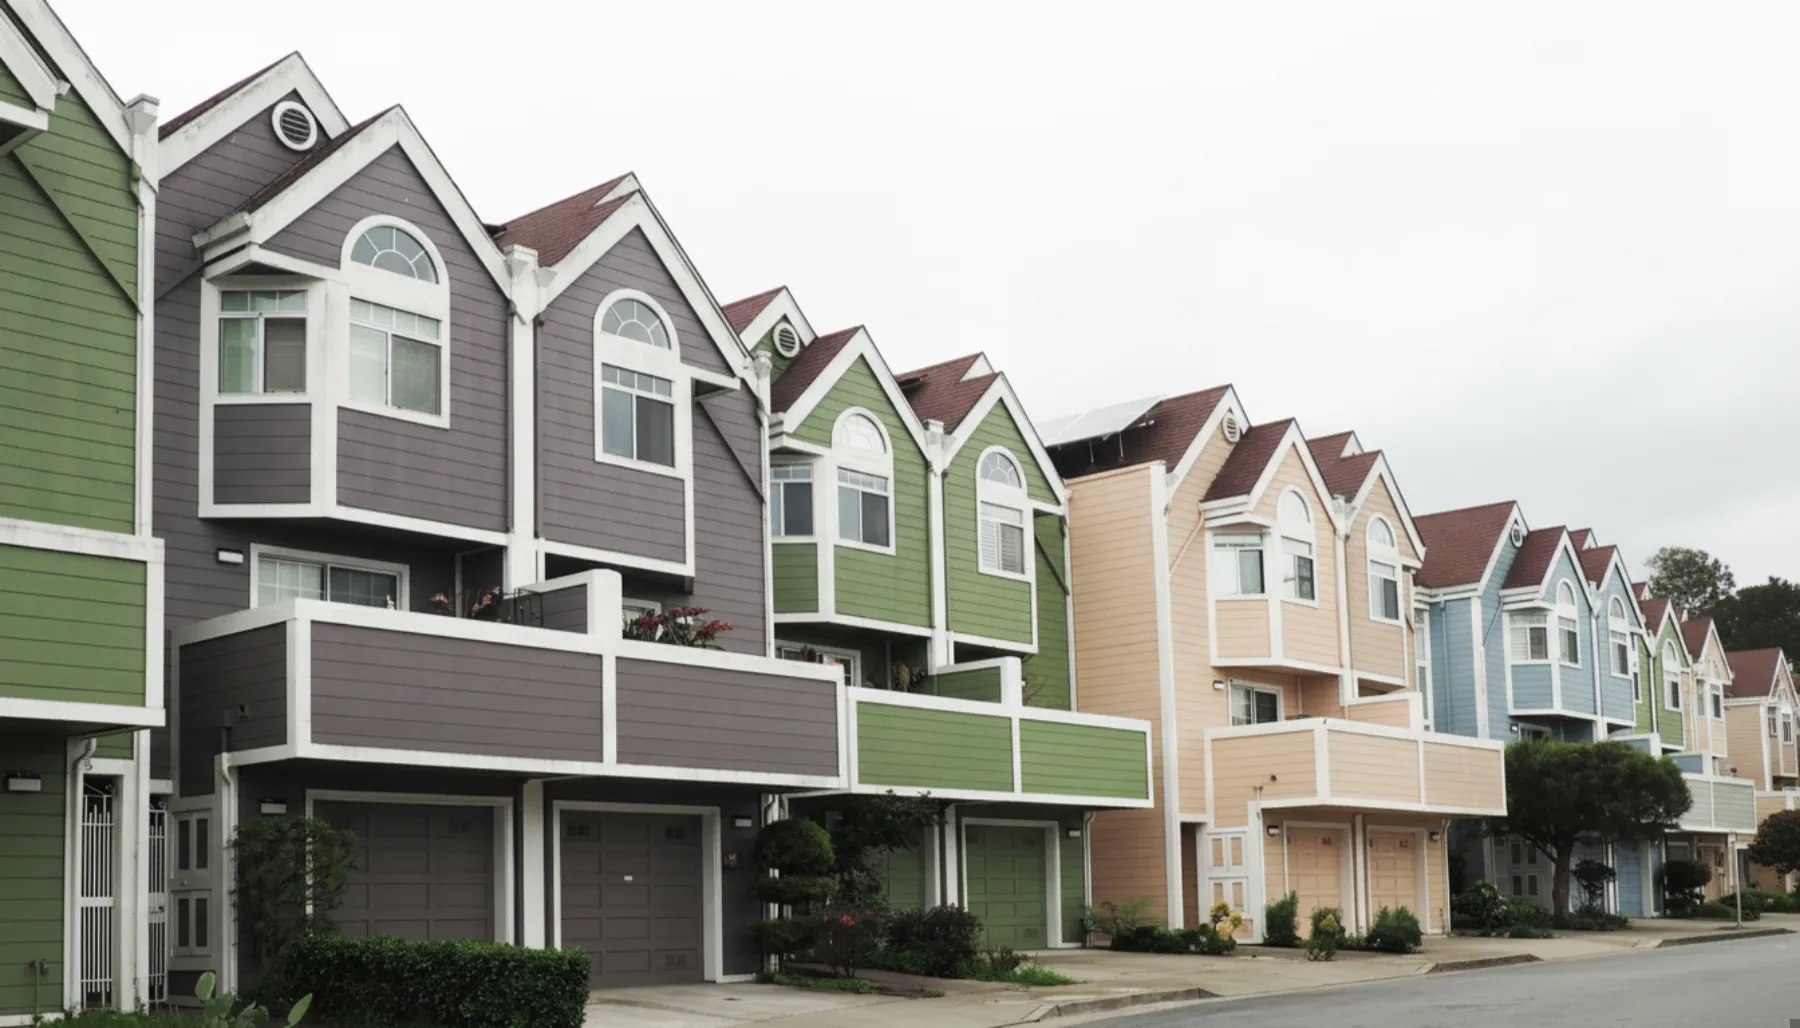
Townhomes represent roughly a third of Chilliwack's housing market, offering a middle ground between detached homes and condos. For buyers seeking lower maintenance, newer construction, and entry-level pricing, townhomes deliver -but financing them involves different considerations than detached properties. Strata fees, insurance requirements, and lender
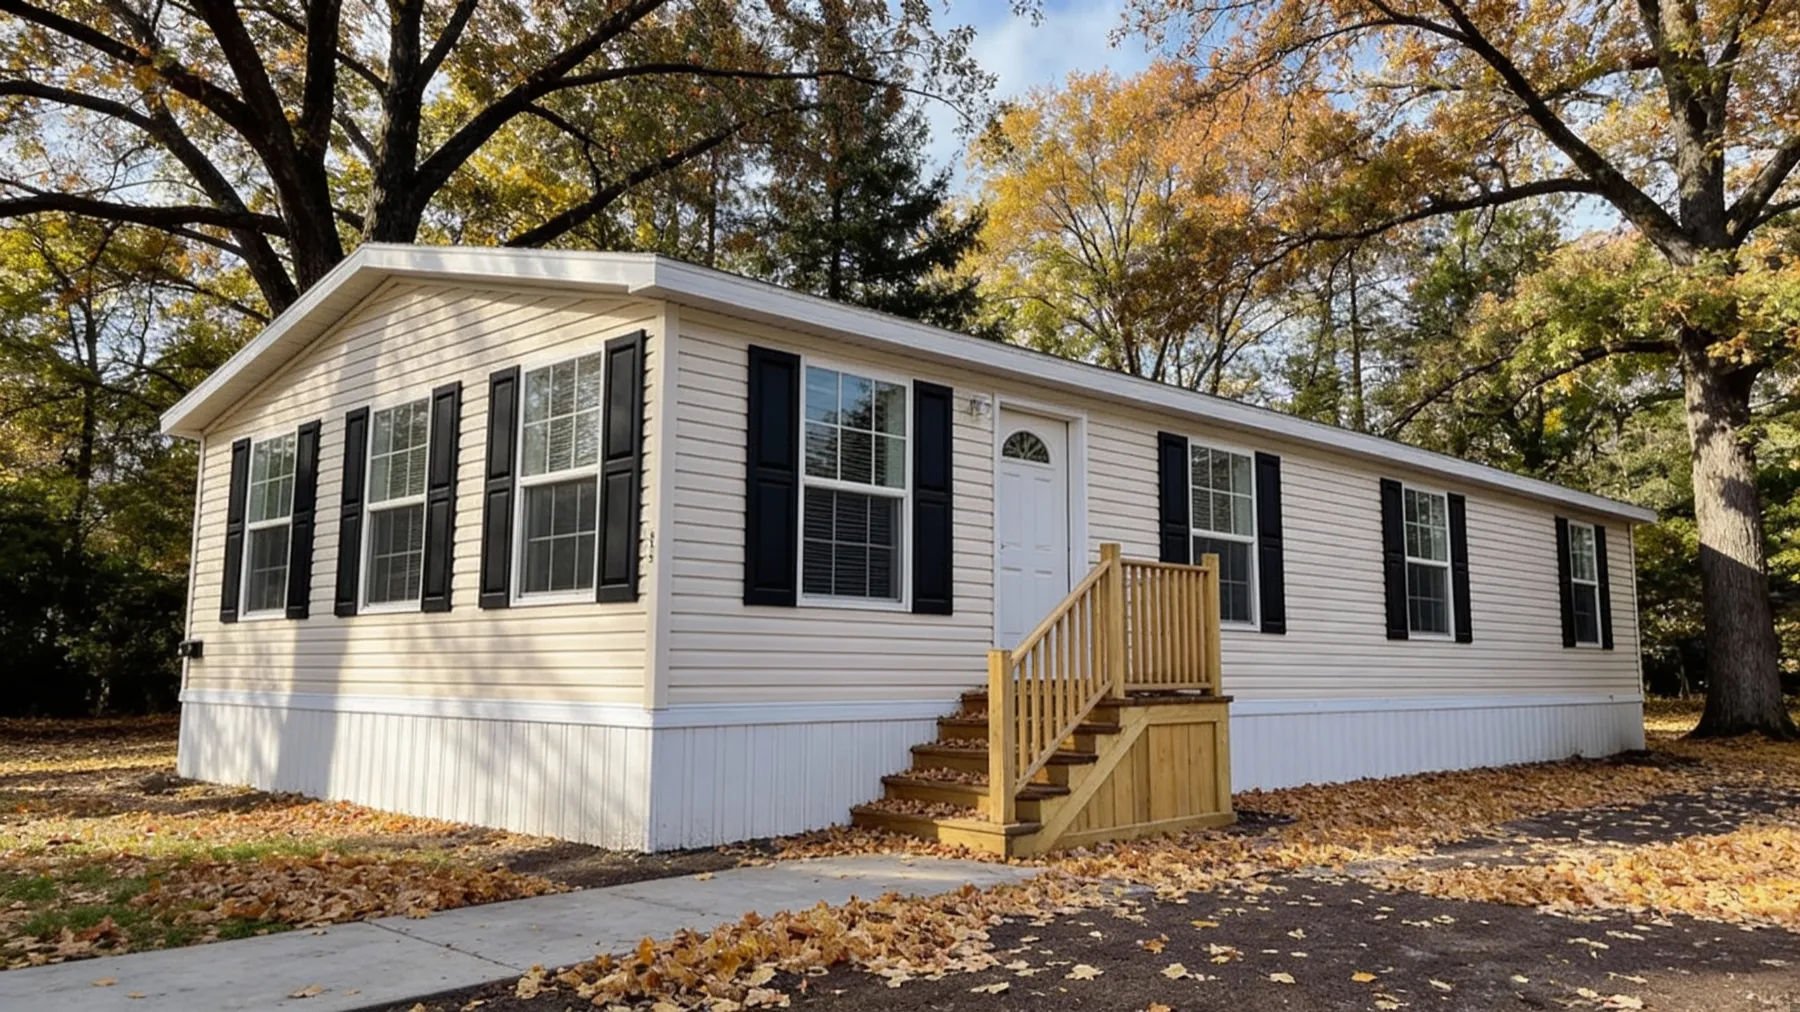
Chilliwack's manufactured and mobile home market represents an often-overlooked path to homeownership. With detached houses pushing $700,000 to $900,000, manufactured homes offer full-sized living spaces at $200,000 to $400,000—sometimes less. But financing these properties involves different rules, lender criteria, and documentation than traditional stick-built homes.
Chilliwack's rural character -rolling farmland, forested hillsides, mountain views, and properties measured in acres rather than square feet -draws buyers seeking space, privacy, and a lifestyle removed from suburban density. But financing a rural property involves considerations that don't apply to in-town homes. Wells, septic
Chilliwack's established neighborhoods -Sardis, Vedder Crossing, downtown core -hold homes built in the 1940s through 1970s, offering character, mature landscaping, larger lots, and lower prices than new construction. But financing an older home involves navigating lender concerns about outdated systems, deferred maintenance, and materials no
Chilliwack's growth -particularly in Sardis, Garrison, and Promontory -brings regular waves of new construction: single-family homes, townhome developments, and mixed-use projects. For buyers seeking modern layouts, energy efficiency, and warranty protection, new builds deliver advantages resale homes can't match. But financing new construction involves different
When you need a mortgage in Chilliwack, you have two main paths: walk into your bank and apply directly, or work with an independent mortgage broker who shops your application across multiple lenders. Both routes can get you financed, but they work differently, and the